

Piggy Bank Allowance - Bomad
Graeme P
- 4.4
- 46.00 Reviews
- 50.00K
- Downloads
- Free
- Price
Screenshots
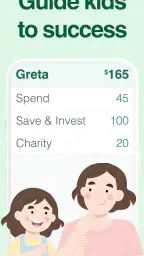
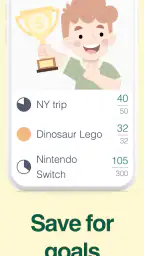
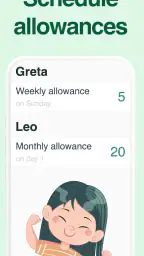
Piggy Bank Allowance - Bomad Pros and Cons
Pros
- Simple way for parents to manage children’s allowances
- Encourages kids to learn saving and money management
- Digital records make allowance payments easy to track
- Useful for setting regular payment routines
- Suitable for families wanting a cashless allowance system
Cons
- May require both parents and children to use compatible devices
- Some features may depend on account setup or permissions
- Children without personal devices may have limited access
- Digital allowances may not suit families preferring cash
- Availability and payment options can vary by region
 Analysis by All-app
I found Piggy Bank Allowance - Bomad most useful as a simple family routine rather than as a full financial education platform. It gives parents and children a shared way to record allowance, divide money between saving and spending, and make progress visible without handing over real cash every time. That basic idea sounds modest, but it can remove a surprising amount of confusion from weekly pocket-money conversations.
I tested it with the mindset of a parent who wants fewer arguments about whether an allowance was paid, where money should go, and whether a child has saved enough for a small goal. The app is free to start, is rated for Everyone, and comes from developer Graeme P. Its focus is narrow: virtual pocket money organized around saving and spending jars or pots. That narrow focus is also its main strength, because it avoids burying a child’s first money lessons under charts and complicated budgeting tools.
How the allowance routine feels in everyday use
The clearest way to understand the app is to imagine a normal Saturday morning. A child has completed the week’s agreed responsibilities, and the parent records the allowance digitally instead of searching for coins. The child can then see money assigned to a saving pot, a spending pot, or another purpose chosen by the family. Later, when the child asks whether a toy is affordable, the answer can be checked together rather than estimated from memory.
That shared view is more valuable than it may first appear. Physical cash can disappear into drawers, pockets, or school bags, while verbal promises about allowance are easy to forget. A digital record gives the family a common reference point. I would use it especially with children who are old enough to understand simple totals but still need help connecting an action today with a purchase later.
The app is not trying to replace a bank account. The balances are a teaching and tracking tool, not a way to move actual money. That distinction matters. Parents should explain that a number in a jar represents an agreed family record, while real spending still requires the parent’s approval and real payment method. Used honestly, this limitation becomes a useful lesson instead of a problem.
I also like the jar-and-pot language for younger users. “Saving” and “spending” are easier concepts to grasp when they are represented as separate places for money. A child can understand that taking money from the spending pot reduces what remains there, while leaving the saving pot untouched protects a longer-term goal. This is more concrete than showing a single balance and repeatedly explaining why it should not all be spent.
Who will get the most from it
Piggy Bank Allowance - Bomad suits families that want a lightweight allowance tracker, particularly when parents and children are still establishing the habit. It can work well for a child receiving regular pocket money, a family using chores as one part of its allowance system, or siblings who each need a visible personal balance. The app is also a reasonable fit when parents want to discuss saving without opening a genuine financial account for a child.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I would be more cautious about using it as the only system for older children who need detailed budgeting, bank integration, transaction history, or independent payment controls. A teenager managing transport, meals, subscriptions, and irregular income will probably outgrow a jar-based tracker. In that situation, a spreadsheet or a supervised youth banking product may offer better records and stronger real-world practice.
It is also not the right choice for a family that wants allowance to run completely automatically. The usefulness depends on adults and children consistently recording the agreed money and discussing changes. If nobody updates the routine, the displayed balance will stop reflecting the family’s understanding, and trust in the system will fade quickly.
Making the jars teach something instead of just displaying numbers
The most effective setup is to decide the purpose of each pot before entering any allowance. I would avoid creating several vague categories at the beginning. A saving pot with a clear goal, such as a book, craft kit, or day out, gives the child a reason to wait. A spending pot can cover small choices now. If a third pot is used, it should have a specific family meaning rather than becoming another unexplained balance.
A useful workflow is to agree on the split before payday, record the allowance, and then ask the child to explain what changed. That small conversation turns the app from a parental ledger into a shared learning exercise. The parent does not need to lecture about finance; the jars provide a visual prompt. Over time, the child begins to see that saving is not simply “having less,” but choosing what the money is meant to do.
Another practical tip is to review the saving goal when it is close to completion. Children can lose interest when a target feels distant, so I would use the app during a short weekly check-in and connect the balance to a real-world plan. If the goal changes, record that decision openly rather than quietly moving money. The important lesson is not only how much has been saved, but that money decisions should be visible and agreed.
What parents should clarify before handing over the phone
The app’s child-friendly concept does not remove the need for family rules. Before using it, I would agree on who may add allowance, who may move money between pots, and whether a child can request a spending change without a parent present. These decisions are more important than the labels themselves. A beautifully organized balance is still confusing if the family has different ideas about what each number represents.
I would also explain the difference between recording a payment and authorizing a purchase. A child may see enough in the spending pot for a desired item, but that does not automatically mean the item should be bought. Price, suitability, timing, and household rules still belong in the conversation. Keeping that boundary clear prevents the app from being mistaken for a payment wallet or a promise that every displayed balance is immediately spendable.
For separated households or families with more than one caregiver, consistency deserves special attention. If one adult records allowance and another changes the arrangement without discussing it, the child may experience the tracker as unfair even when the totals are technically correct. I would agree on one routine for updates and use the same definitions for allowance, bonus money, and deductions. The app can support a shared process, but it cannot settle disagreements between adults.
Trust, controls, and moments that deserve care
I treat trust as a routine the family builds, not something a displayed balance can guarantee. Before a child uses the tracker independently, I would agree on who can update it and explain that its jars record family decisions rather than holding real money; that gives us a clear starting point for considering the controls and sensitive moments that follow.
What can reasonably be trusted about the app’s role
My trust in Piggy Bank Allowance - Bomad comes mainly from keeping its role limited and understandable. It presents itself as an allowance and virtual pocket-money tool, not as a substitute for a bank. That makes it easier to explain to a child and reduces the risk of confusing a teaching balance with money held by a financial institution. The developer is listed as Graeme P, and the app has reached over fifty thousand installs with an average rating of 4.4 from around seven hundred ratings, which suggests that the basic idea has found a real audience.
Those figures do not prove that every family will find the experience perfect, but they do make the app feel established enough to consider rather than experimental in the everyday sense. I would still judge it by the family’s routine, not by popularity. An allowance tracker is only trustworthy in practice when its records match the agreements adults and children make outside the screen.
The app is free, which lowers the barrier to trying it with a family. There are in-app purchases ranging from $1.99 to $29.99 per item, so I would review the purchase choices before allowing a child to explore independently. This is not a reason to reject the app, but it is a reason to keep purchasing under adult control and to make sure everyone understands which parts of the experience are free and which may involve payment.
Permissions, data choices, and account boundaries
When I assess a parenting app, I pay attention to moments where a child might enter personal information, where an adult might assume a balance is private, and where a purchase could happen without a clear decision. With this app, parents should treat the initial setup as a supervised activity. Use only the information needed for the allowance routine, avoid entering sensitive family details into labels, and make sure children know not to add names, addresses, school information, or other personal details to notes or goals.
I would also check the device’s permission prompts and the app’s visible privacy choices during installation and setup. Permissions should make sense for an allowance tracker. If a prompt is unclear, I would pause rather than approve it automatically. This is a good general habit with any parenting app, especially when a child may use the device later and assume that every request is part of the game or allowance process.
Account control matters just as much. The parent should be the person who manages purchases, decides who can edit balances, and chooses whether the child uses a shared device or a separate one. If the app is installed on a family tablet, I would use the device’s own profile, passcode, or purchase restrictions where available. That adds a layer of practical protection without pretending that an allowance tracker can provide bank-level security.
There is also a social privacy issue that parents sometimes overlook. A child’s allowance balance can feel personal even when it is not financially sensitive in the formal sense. I would avoid displaying the jars in front of siblings or guests unless the child is comfortable with it. The app works best as a cooperative family tool, not as a public scoreboard that invites comparisons over who has saved more.
Where user agency is strong and where it depends on adults
The jar model gives children a meaningful choice: they can see money separated by purpose and participate in decisions about saving or spending. That is stronger than a tracker that only shows a total. A child can ask to move money, postpone a purchase, or set a new goal, and the parent can use that request as a chance to explain trade-offs. The visible structure supports agency without requiring the child to manage a real bank account.
At the same time, the parent remains the authority over the record. That is appropriate for younger children, but it means the app should not be presented as an independent financial tool. If a child cannot tell whether a parent changed a balance, the learning value suffers. I recommend narrating important edits: explain why an allowance was added, why a purchase reduced a pot, or why a goal was changed. Transparency is more educational than simply handing the phone over.
A particularly useful approach is to let the child make the first proposal. For example, the parent can ask how a new allowance should be divided, then discuss whether the plan leaves enough for the child’s short-term choice. This creates a real trade-off instead of turning the jars into fixed parental instructions. The app becomes a place to practice decisions, while the family remains responsible for the boundaries.
How it compares with cash, spreadsheets, and banking alternatives
Compared with cash in envelopes, the app is easier to review and less likely to disappear physically, but it is less tangible. Some children understand money faster when they can hold coins and watch an envelope become empty. I would choose the app for visibility and consistency, or combine it with occasional real cash when the lesson calls for physical counting. The two approaches do not have to compete.
Compared with a spreadsheet, the app should feel more approachable for a child because the jar concept is immediately understandable. A spreadsheet can handle irregular payments, detailed notes, multiple caregivers, and long-term records more flexibly, but it may turn allowance into an adult-managed document. Families with complicated rules may prefer a spreadsheet, while families trying to build a simple weekly habit will likely appreciate the more focused presentation here.
Compared with a youth bank account, this app is safer as a first conceptual step because it does not make a child responsible for genuine transactions. A bank account is better when the goal is supervised independence, learning about statements, or using real payment tools. Piggy Bank Allowance is better when the main question is, “How do we make saving and spending understandable at home?” Choosing between them depends on the child’s maturity and the family’s purpose, not on which product has more features.
Limitations I would want families to accept upfront
The narrow scope can become repetitive if the family expects a complete money-management system. The app is built around allowance and pots, so it may not satisfy parents looking for extensive reporting, investment education, bill tracking, or automatic links to financial accounts. I would not install it expecting those functions. Its value comes from doing one family task clearly.
There is also a human limitation: the app cannot know whether a chore was completed fairly, whether an allowance should be withheld, or whether a purchase fits the family budget. Those decisions remain outside the screen. If parents use deductions unpredictably, the child may learn that the balance is controlled by mood rather than by an agreed rule. The best results come when the app records a policy that already exists instead of becoming the policy itself.
Finally, any digital record can become stale. A child may receive money from a grandparent, spend cash at a market, or promise to save part of a gift without anyone entering it. I would schedule a quick review after unusual events and keep the language simple: what came in, what went out, and what each pot is for. That small discipline is essential if the app is to remain a trusted reference.
My cautious recommendation
I recommend Piggy Bank Allowance - Bomad to parents who want a clear, low-pressure way to introduce saving and spending conversations. Its free entry point, Everyone age rating, and focused jar system make it approachable for families that do not need a real financial account yet. The current version is 2.0.266, and the app has been available since March 24, 2023, giving it a reasonable period of availability while keeping the experience centered on a straightforward household routine.
I would install it with the parent in charge of setup and purchases, discuss privacy and editing rules before involving the child, and treat every balance as a family record rather than real stored money. I would also avoid creating too many pots, set one concrete saving goal, and review the arrangement regularly. Those steps make the app more useful than simply entering an allowance and leaving the child to interpret unexplained numbers.
My final view is positive but deliberately limited: this is a practical teaching aid, not a complete youth banking solution. If your family needs a visible bridge between allowance and basic money decisions, it is worth trying. If you need automation, detailed financial history, or independent spending controls, choose a more advanced alternative. For the right age and the right household routine, Piggy Bank Allowance - Bomad makes an often messy conversation easier to see, discuss, and repeat.
Frequently Asked Questions
What is Piggy Bank Allowance - Bomad, and who is it designed for?
Piggy Bank Allowance - Bomad is a family-focused allowance management app designed to help parents and children organize pocket money, savings goals, and everyday financial habits. Parents can use it to record or manage allowances, while children can see how much they have earned, saved, or spent. It is especially useful for families introducing basic money-management concepts in a simple, visual way.
How does the allowance system work in Piggy Bank Allowance - Bomad?
The app allows families to establish an allowance routine based on their own rules, such as weekly payments, completed chores, or occasional rewards. Parents can typically keep track of transactions and update balances, while children can follow their progress toward saving goals. Before downloading, it is worth deciding whether you want to use the app as a simple record-keeping tool or as part of a broader chores-and-rewards system.
Does Piggy Bank Allowance - Bomad handle real money or make payments?
Piggy Bank Allowance - Bomad should be understood primarily as an allowance and money-tracking tool rather than a replacement for a bank account. Families can use it to record virtual balances, planned allowances, savings, or spending, but users should verify the current app description to confirm whether any banking, payment, or transfer features are available in their region. Do not assume that an in-app balance represents money held by a financial institution.
Is Piggy Bank Allowance - Bomad suitable for young children?
The app can be suitable for children because allowance and savings information is generally easier to understand when presented visually and in a dedicated family app. However, the ideal age depends on the child’s reading ability, independence, and how much supervision parents want to provide. Parents should configure the system together with their children, explain that digital balances are records of real-world agreements, and avoid sharing sensitive account details.
What should parents check before downloading Piggy Bank Allowance - Bomad?
Before installing Piggy Bank Allowance - Bomad, parents should review the latest privacy policy, permissions, subscription details, supported devices, and whether the app includes advertising or optional purchases. It is also important to check how data is backed up, whether multiple family members can access the same information, and whether the app works offline. These details can change with updates, so checking the official store listing is recommended.


